
Understanding the Recent Tech Market Correction
Financial markets recently experienced a notable shift in sentiment regarding technology hardware companies. Equity values for major component manufacturers faced severe downward pressure as investors reassessed the sustainability of rapid growth in the sector. Among the affected firms, memory and storage producer shares registered a dramatic single day decline of seventeen percent.
This sharp correction reflects a growing cautiousness across global exchanges. Market participants are carefully evaluating whether current capital expenditure levels in advanced technology infrastructure can maintain their current pace. The swiftness of the repricing highlights the sensitivity of growth-oriented equities to shifting macroeconomic signals and industry forecasts.
Artificial Intelligence Spending Concerns
At the core of the market downturn is an intensifying debate over future demand for specialized processing hardware. Financial analysts note that enthusiasm surrounding artificial intelligence initiatives may have outpaced immediate commercial deployment realities. Consequently, stakeholders are questioning the timeline for return on investment regarding massive data center builds and advanced computing deployments.
Component suppliers heavily rely on sustained high-volume orders to justify extensive capital investments in fabrication facilities. When market participants perceive a potential deceleration in end-user demand or a normalization of purchasing cycles, share prices tend to react violently. The recent contraction underscores the vulnerability of high-multiple stocks to any sign of slowing momentum in the technology hardware ecosystem.
Supply Chain and Infrastructure Developments
Adding to the downward pressure on equity valuations were reports regarding adjustments to production infrastructure. News surfaced indicating a temporary pause in construction activities at a key manufacturing facility located in Taiwan. While operational adjustments are common in complex industrial environments, investors interpreted this development as an additional indicator of softening near-term capacity requirements.
Infrastructure projects of this scale require precise alignment between anticipated market absorption and physical deployment timelines. Any indication that management teams are recalibrating their expansion plans tends to amplify existing anxieties about future supply dynamics. These operational updates compounded the already cautious sentiment prevailing across global technology exchanges.
Technical Indicators and Market Outlook
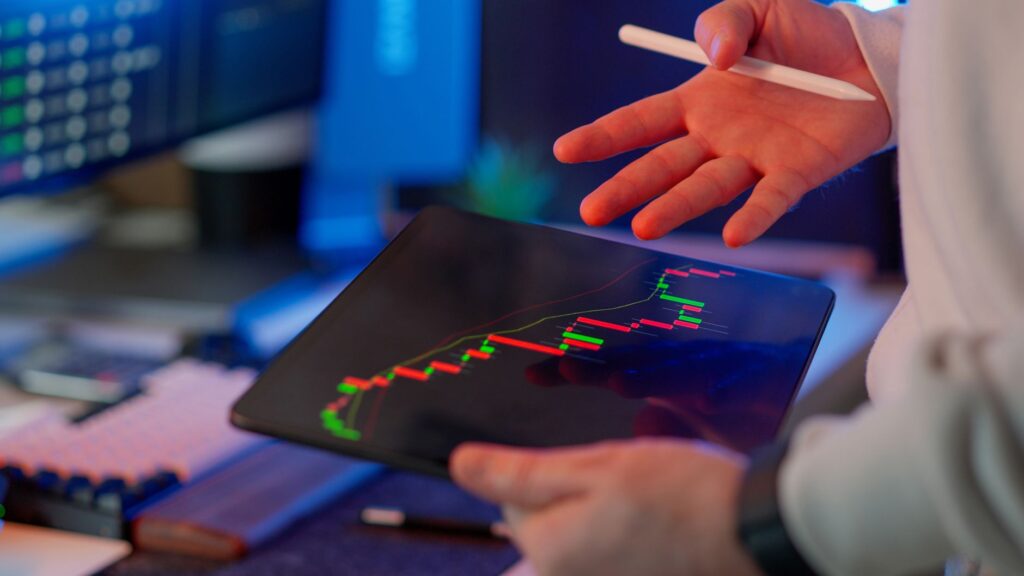
Beyond fundamental concerns regarding industry demand, market mechanics also played a role in the magnitude of the recent price movement. Technical analysis indicators suggested that the equity had entered deeply oversold territory during the accelerated liquidation phase. Such conditions often occur when algorithmic trading models and automated stop-loss mechanisms trigger simultaneous selling orders.
Looking ahead, market observers emphasize the importance of forthcoming earnings reports and corporate guidance to gauge the true state of enterprise demand. While the short-term price action reflects heightened volatility and investor apprehension, long-term industry proponents argue that foundational growth drivers remain intact. Navigating the current environment will require careful monitoring of capital expenditure trends and actual delivery metrics across the broader technology landscape.